A second reported $45 billion agreement would deepen Nscale’s dependence on Anthropic, while financing, power availability, and construction remain critical tests of the AI infrastructure boom.
The AI infrastructure industry has demonstrated a remarkable aptitude for announcing massive financial commitments; however, the more significant challenge lies in translating these figures into operational computing systems.
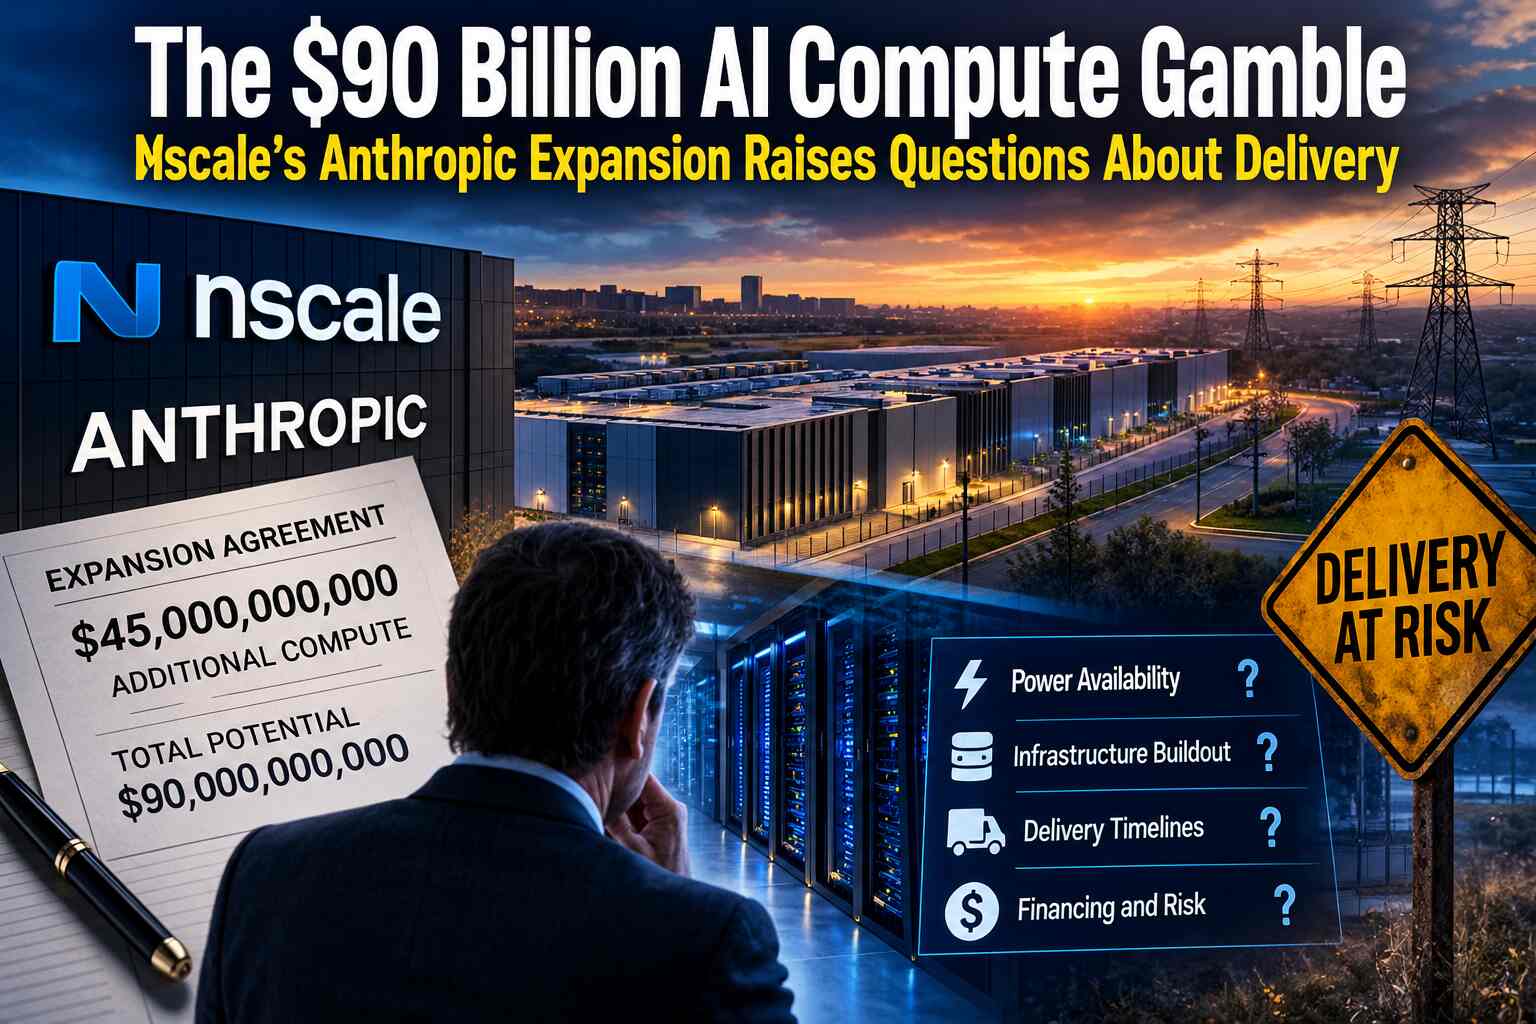
This dichotomy defines the potentially vast expansion involving Nscale, an AI infrastructure provider backed by Nvidia, and Anthropic, the developer of Claude. On October 19, Bloomberg reported that the two companies are negotiating a second cloud computing agreement worth about $45 billion. This proposed deal would support a new 460-megawatt facility at Nscale’s Monarch Compute Campus in West Virginia and may grant Anthropic a right of first refusal on a third facility.
While Reuters covered the report, the outlet could not independently verify the negotiations, and neither company has confirmed the agreement. As a result, this remains an ongoing negotiation rather than a finalized contract.
Ultimately, the broader narrative transcends the timeline of this agreement. Nscale’s own public offering disclosures illuminate the primary challenge facing the AI infrastructure sector: contracted demand often outpaces the physical infrastructure, financing, and operational capabilities necessary to fulfill such commitments.
A $103.4 billion backlog with a delivery problem
Nscale’s September IPO filing reported approximately $103.4 billion in total contracted value as of August 2026, up from roughly $38 billion at the end of 2025. The company’s disclosed agreements include up to approximately $43.8 billion associated with Microsoft and $44.6 billion associated with Anthropic.
Together, those two customers represent roughly 85% of the reported contracted value.
The operational figures tell a very different story. According to the filing figures summarized in reporting on the prospectus, approximately $2.6 billion of the $103.4 billion total was active as of late August. That is about 2.5% of the reported contract value.
The distinction requires care: contracted value is not the same as recognized revenue, cash in the bank, or a measure of computing capacity alone. The agreements span multiple years, and their value depends on services being delivered over time. A low proportion of active contract value does not, by itself, establish that the remaining commitments will fail.
It does, however, expose the scale of the execution challenge.
Nscale must secure financing, obtain hardware, construct facilities, arrange dependable power and cooling, commission systems, and deliver capacity according to contractual milestones. Until those steps occur, much of the reported backlog remains a future obligation rather than an operating AI cloud business.
For HPC customers, the difference is fundamental. A projected GPU deployment is not a production cluster. A building announcement is not a commissioned supercomputer. And a contract for computing capacity is not proof that the capacity will be available when a customer needs it.
The first Anthropic agreement carries conditions
The proposed second agreement would build on an existing Anthropic commitment valued at approximately $44.6 billion, covering 460 MW of computing capacity over six years at the Monarch campus.
Nscale’s IPO disclosures describe important conditions surrounding that first agreement. The company had not secured binding financing commitments sufficient to fund the required buildout, and it had not secured all the long-term chip supply needed to perform its obligations. The filing also describes stringent delivery milestones and provisions allowing Anthropic to cancel affected later tranches without penalty under specified circumstances.
These are not minor details buried beneath an otherwise impressive contract value. They help determine who bears the risk if financing slips, hardware arrives late, construction falls behind schedule, or a facility cannot provide the promised service.
A second agreement could create an even larger opportunity for Nscale. But if the reported terms resemble the first arrangement, it could also increase the amount of future infrastructure the company must finance and deliver for the same customer.
That is the difference between growing a backlog and diversifying a business.
If the second agreement closes at approximately $45 billion, Anthropic’s potential contracted value with Nscale could approach $90 billion. Against a reported total backlog of $103.4 billion, that would represent an extraordinary concentration in one customer, assuming the amounts are additive and the other commitments remain unchanged.
The figure should not be mistaken for guaranteed revenue. It represents the potential scale of the contractual relationship, not cash already earned or infrastructure already operating.
A 460-megawatt facility is an engineering undertaking
The Monarch project illustrates why AI infrastructure cannot be evaluated solely by counting accelerators or comparing announced capital commitments.
A 460 MW data-center deployment requires much more than racks of Nvidia Vera Rubin systems. It needs electrical infrastructure capable of delivering power reliably, cooling systems designed for sustained high-density computing, network fabrics that connect accelerators at scale, storage infrastructure able to feed workloads, and operational systems to monitor and maintain the entire environment.
Those subsystems must work together.
In large distributed AI training jobs, a shortage of power or a cooling limitation can prevent an otherwise expensive cluster from reaching its intended operating capacity. Network congestion, insufficient storage throughput, failed components, or poorly coordinated system software can further reduce the useful work delivered by the installed hardware.
The facility must also be commissioned in stages. Equipment deliveries, electrical acceptance testing, cooling validation, networking integration, and workload qualification all have to align with the promised service schedule.
That makes the reported second 460 MW facility a substantial construction and systems-integration challenge, not merely another order for GPUs.
The schedule matters, too. The existing Monarch deployment has been associated with a planned rollout of next-generation Vera Rubin systems beginning in late 2027. A second facility would introduce additional dependencies involving hardware availability, construction progress, and power delivery. Neither the proposed deal nor its final implementation schedule has been confirmed.
For the HPC community, the relevant question is not simply how many accelerators Anthropic may eventually rent. It is how much usable compute Nscale can bring online, when it can deliver it, and at what level of reliability.
Microsoft’s withdrawal underscores the power constraint
The concerns are not hypothetical.
On October 19, Reuters reported that Microsoft had withdrawn from a planned Nscale data-center project in Loughton, England, after delays involving access to the electricity grid. Reuters’ Breakingviews analysis highlighted the wider risk for infrastructure providers that have signed large commitments before all the necessary capacity is ready.
The withdrawal concerns a particular project; it does not establish that Microsoft has abandoned its broader relationship with Nscale or that the Monarch campus will suffer the same outcome. Nevertheless, it demonstrates that access to electricity can become a decisive constraint even when a major customer and a technology supplier are already lined up.
Monarch also has an energy dimension of its own. The vetting material identifies Caterpillar natural-gas generator sets as part of the campus’s planned behind-the-meter power strategy. On-site generation may provide an alternative or supplement to grid supply, but it introduces its own engineering, fuel-supply, permitting, emissions, and operating considerations.
A generator installation is not automatically equivalent to a fully engineered, permitted, and dependable power system for a campus operating at hundreds of megawatts.
The question is whether the entire energy plan can support the facility’s commissioning schedule and sustained computing demand. That requires more than a projected capacity figure.
For an industry increasingly constrained by electricity availability, the power system is part of the supercomputer.
The financial structure deserves the same scrutiny as the hardware
Nscale’s proposed public offering adds another layer to the story.
The company’s filing outlined a planned listing and a potential fundraising target of up to $3 billion, with reporting placing its valuation ambitions as high as $35 billion. Its first-half 2026 financial results showed revenue of approximately $140.6 million and a net loss of approximately $1.02 billion, compared with revenue of $10.4 million and a loss of approximately $369 million in the same period a year earlier.
Those figures reflect a company investing heavily in growth, but they also demonstrate the distance between its current financial performance and the scale implied by its contracted commitments.
The proposed second Anthropic deal arrives at a time when Nscale needs to convince investors that its future obligations can become a functioning, revenue-generating infrastructure business.
That timing warrants scrutiny, not an assumption of misconduct. The reported negotiations may represent genuine customer demand and a commercially valuable expansion. But an unconfirmed agreement should not be treated as though it has already improved the company’s cash flow, funded its construction programme or reduced its execution risks.
Investors need to distinguish signed agreements from negotiations, conditional commitments from unconditional ones, and announced financing from binding funding available when construction bills come due.
Nvidia’s position is also relevant. The company is both a major participant in the AI hardware ecosystem and a reported $1 billion investor in Nscale’s pre-IPO convertible financing. That relationship does not invalidate Nscale’s business, but it illustrates how closely capital providers, accelerator suppliers, and AI infrastructure operators can be connected.
The industry’s expansion increasingly relies on an interconnected group of companies funding, supplying and purchasing capacity from one another. Such relationships can accelerate deployment, but they also make it essential to understand who ultimately bears the financial risk if expected demand, construction schedules or equipment deliveries change.
Anthropic has options. Nscale must deliver.
Anthropic’s broader computing strategy makes the proposed expansion particularly interesting.
The AI developer has pursued capacity through multiple cloud and infrastructure relationships, including major arrangements involving Google, Amazon Web Services and other providers. Its reported negotiations with Nscale therefore sit within a wider effort to secure enough computing capacity for future model development and deployment.
For Anthropic, securing future capacity across several providers can reduce dependence on any single infrastructure project, although individual agreements may still impose substantial commitments.
For Nscale, the calculus is different. The company must build the facilities and procure the systems that turn those commitments into services. If the customer has contractual rights to cancel affected tranches when specified milestones are missed, Nscale faces a potential mismatch between infrastructure costs and the revenue it expects to earn.
That asymmetry is central to the story. Anthropic is competing to secure future compute. Nscale is competing to demonstrate that it can supply it.
A second contract could strengthen the commercial relationship, but it would not automatically resolve the financing, power, construction and delivery questions surrounding the first.
What HPC operators should watch next
Several milestones will reveal more than another headline about contract value.
First, watch for confirmation of the proposed second agreement and its actual terms. The critical details include delivery dates, cancellation provisions, capacity milestones, and whether the arrangement depends on financing or other conditions.
Second, look for evidence of binding project financing and secured hardware supply. A credible delivery plan must connect the funding timetable with equipment procurement and construction milestones.
Third, track physical progress at Monarch: permits, power availability, facility commissioning, cooling validation, networking readiness, and the number of megawatts that are actually serving workloads.
Fourth, examine the distinction between installed hardware and usable compute. Accelerator counts alone do not establish delivered performance. HPC customers ultimately need reliable service, predictable availability, and systems capable of sustaining demanding workloads.
Finally, watch customer concentration. If Microsoft and Anthropic continue to account for most of Nscale’s contracted value, the company’s outlook will remain heavily influenced by the investment decisions and contractual rights of those two customers.
These are measurable questions. They offer a firmer basis for assessing the project than treating a potential $45 billion agreement as proof of future success.
The bottom line: Backlog is not compute
The AI industry necessitates substantial infrastructure investment, and Nscale’s reported negotiations with Anthropic underscore the magnitude of this demand. A second 460 MW facility at the Monarch campus could serve as a significant source of future computing capacity, contingent upon the finalization of the agreement and the successful financing, construction, and commissioning of the project.
However, as the second agreement remains unconfirmed, the conditional nature of the initial contract highlights that project execution is a critical challenge rather than a peripheral detail.
Nscale’s reported $103.4 billion backlog reflects the scale of the opportunity it is pursuing. Nonetheless, the modest percentage of active contract value, the reliance on a limited number of major customers, and the inherent complexities regarding financing and power procurement demonstrate why this opportunity cannot be assessed solely by its headline figure.
For the supercomputing industry, the definitive metric is not the valuation of a contract or the number of GPUs allocated for a future site. Rather, it is the computing capacity that can be reliably delivered, sustainably powered, and scaled effectively. In the realm of AI infrastructure, a multi-billion-dollar contract represents a promise; a fully operational supercomputer constitutes proof.